
Chargeback Statistics 2026: 25+ Facts on Fraud, Costs & Trends


According to Mastercard and Datos Insights, chargeback statistics for 2025 project 261 million disputes worldwide, rising to 324 million by 2028, and about 74% of those disputes go all the way to a full chargeback. Fraud now costs US merchants $4.61 for every $1 they lose, per LexisNexis.
Every other roundup repeats the same Mastercard and Visa figures. We're adding the networks, reason codes, and countries behind 1.8 million alerts in our own dataset.
Check your numbers against real ones.
Key takeaways
- Global chargeback volume reaches 261 million in 2025, 324 million by 2028.
- US merchants lose $4.61 for every $1 of fraud.
- US merchants win about 54% of the disputes they choose to fight.
- About 74% of all disputes end as full chargebacks.
- Merchants win only 8.1% of all disputes outright, once issuer decisions count.
- Only 9.9% of disputed transactions in our data had 3D Secure enabled.
Stop disputes before they become chargebacks. See how our alerts work.
How big is the global chargeback problem right now?
Global chargeback volume is projected to reach 261 million disputes in 2025 and 324 million by 2028, a 24% jump in three years. In dollars, that is $33.79 billion disputed in 2025 rising to $41.69 billion by 2028.
In the US alone, $34 billion in card transactions was disputed and charged back to merchants in 2025.
For the underlying mechanics, read our guide to what a chargeback is.
Two things drive the growth. Card-not-present spending keeps rising, so more charges happen without the customer holding the card. Subscription billing keeps growing too, so more charges land months after the customer last thought about buying.
Either way the customer ends up staring at a line on a statement they can't place.
Growth is also uneven by region, and the fastest-growing markets are not the biggest ones:
North America still files the most disputes by a wide margin, and per Datos Insights' data, it is growing the slowest at 16%. The Middle East and Africa nearly quadruple that growth rate off a smaller base.
Why does chargeback volume keep rising?
About 74% of disputes end as full chargebacks, because customers call their bank first and the bank files it. In the US, cardholders go straight to their issuer in about 75% of disputes.
That leaves a quarter where the merchant hears about it first.
According to Javelin Strategy & Research, those merchants fix it 44% of the time just by answering the question. Another 31% end with a refund, a replacement, or a cancelled subscription.
The banking apps are part of it. Disputing a charge takes a few taps in an app the cardholder already has open. Contacting the merchant means finding a support email and waiting. Issuers built that flow to keep cardholders happy, and it works.
Why issuers say disputes are growing
Issuers blame awareness before fraud, and by a wide margin. According to Javelin's issuer survey, asked what changed, 83% pointed to consumers knowing the dispute process better:
| Reason issuers cite | Share of issuers |
|---|---|
| More consumer awareness of the dispute process | 83% |
| Increase in first-party fraud | 49% |
| Increase in card-not-present transactions | 48% |
| Heightened spend tracking by consumers | 41% |
| Easier dispute channels, like mobile banking | 25% |
Awareness leads at 83%, far ahead of first-party fraud at 49%. More people know the dispute button is there, so more of them press it.
Cardholders now shop for that convenience. Easy disputes rank third in what people want from a new credit card, behind only customer service and issuer reputation.
Javelin ran the numbers on what that costs merchants:
"If consumers contacted merchants first 100% of the time, chargeback and retrieval volume could be easily reduced by 50% to 60%."
Javelin Strategy & Research, Chargebacks: The Case for Coordination (January 2026)
The cheapest fix is a quick conversation, and it almost never happens.
A merchant could have answered "that charge is your March renewal" in one reply. Instead they get a chargeback, a fee, and a lost sale.
Merchants agree the balance is off. 77% say it is too easy for customers to dispute a transaction. Another 73% say they could have fixed the problem directly, had they known before it became a chargeback.
What causes most chargebacks?
According to Mastercard and Datos Insights, fraud of some kind drives about 45% of chargebacks, and the rest are disputes over the goods or the billing. Here is how merchants split the causes:
| Dispute category | Share of chargebacks |
|---|---|
| Third-party (criminal) fraud | 38% |
| First-party fraud | 25% |
| Non-fraud disputes | 21% |
| Low-dollar write-offs | 16% |
A lot of what lands in those buckets starts as confusion. Half of consumers questioned a purchase on their statement last year. Of those, 24% did it because they didn't recognize the details.
First-party fraud, also called friendly fraud, is when the real cardholder disputes a charge they actually made.
Our own alert data shows the same pattern for our merchants when you look at reason codes. You can look up any code yourself. In our dataset, the top five codes behind disputed alerts run like this:
| Reason code | Meaning | Share of coded alerts |
|---|---|---|
| 10.4 | Visa, fraud on a card-absent transaction | 11.1% |
| 13.2 | Visa, cancelled recurring transaction | 8.5% |
| 13.7 | Visa, cancelled merchandise or services | 8.2% |
| 4853 | Mastercard, cardholder dispute | 6.7% |
| 4837 | Mastercard, no cardholder authorization | 5.5% |
Two of those top three describe a subscription or an order the customer wanted to end.
Cancelled-subscription disputes are their own problem, and our guide to chargebacks in SaaS covers how to stop them.
Who you ask changes the answer, though. A bank codes what the cardholder claimed, while a merchant sees the order history behind it. Mastercard's data shows issuers label 72% of disputes as fraudulent against 45% for merchants, a 27-point gap on the same transactions. So "how many chargebacks are fraud" depends on which side filled in the survey.
How much of it is friendly fraud?
Friendly fraud is the fastest-growing slice of the mix. Visa puts it at around 20% of all fraudulent disputes globally, and up to 30% for high-volume online merchants. Juniper Research expects it to climb from 22% of chargebacks in 2026 to 28% by 2031.
Datos Insights projects first-party fraud cases rising from 30.6 million in 2025 to 38.2 million by 2028.
The behavior repeats. About half of friendly fraudsters file again within 60 days of a win. Between 10% and 16% of consumers admit to disputing a charge they made.
We break the categories apart in our comparison of friendly fraud and true fraud.
Summary:Fraud leads by category, but cancelled subscriptions and unrecognized charges drive more disputes combined.
Biggest chargeback trends right now
Four shifts are driving dispute volume in 2026, and only one of them is criminal fraud. Each one changes what a merchant should watch:
- First-party fraud keeps climbing, and merchants feel it more than issuers do.
- Filing a dispute got easy, so more customers file one.
- Card-not-present volume keeps growing, which widens the exposure.
- Billing descriptors still confuse people, which turns real purchases into disputes.
1. First-party fraud keeps climbing
Six in ten merchants report first-party misuse rising. Merchants and issuers used to disagree sharply about how much of it there was. According to Javelin's merchant and issuer surveys, in 2018 merchants put friendly fraud at 34% of disputes while issuers said 17%. By 2025 the two had nearly converged, at 20% and 19%.
| Share of disputes believed to be friendly fraud | 2018 | 2025 |
|---|---|---|
| What merchants believed | 34% | 20% |
| What issuers believed | 17% | 19% |
Both sides now track disputes more closely, which is why the estimates moved together.
2. Filing a dispute has become too easy
83% of issuers say growing consumer awareness is behind their rising dispute volume. Customers learned the dispute button exists, and mobile banking put it two taps away.
Merchants see the same thing from the other side. 77% say disputing is too easy, and 78% say the process favors issuers over them.
3. Card-not-present exposure keeps growing
According to Mastercard's merchant survey, digital purchases now make up 63% of merchant transaction volume. Another 48% of issuers tie their rising dispute counts to card-not-present growth.
Card-not-present means the cardholder never physically presents the card. There is no in-person moment to anchor the memory of buying.
4. Descriptors still cause disputes
Unrecognized statement lines still turn real purchases into disputes. The descriptor numbers above put roughly a quarter of questioned purchases in this bucket, which makes it the largest avoidable category on the list.
Fixing the descriptor is the cheapest prevention work available, because it stops the dispute before anyone files anything.
Summary: Awareness, easy filing, and card-not-present growth drive volume more than criminal fraud does.
What prevention tools do merchants use?
79% of merchants run a third-party service or platform to manage chargebacks and retrieval requests. Very few handle the workflow entirely in-house.
service or platform
in-house
Both sides of the network want the same fix, and it is data rather than software:
| What would help | Issuers endorsing | Merchants endorsing |
|---|---|---|
| Shipping and delivery confirmation shared at settlement | 91% | 77% |
| Item or subscription details shared at settlement | 75% | 36% |
| Merchant joins the conversation before the dispute is filed | 82% | 18% |
Issuers want the merchant's shipping data far more than merchants expect them to. Javelin's survey puts the 91% against 77% gap on delivery confirmation as the clearest agreement in the whole dispute chain.
Dispute alerts do the same job on a shorter timeline. An alert reaches the merchant while the dispute is still with the issuer. That leaves room to refund the customer before a chargeback is filed.
Ethoca is one of the largest alert networks running that timeline for merchants today.
Our guide to chargeback alerts explains how each network delivers them.
What does a chargeback actually cost?
Fraud costs US merchants $4.61 per $1 lost. Each dispute also costs a bank $9.08 to $10.32 in staffing alone. That multiplier exists because the disputed amount is only the first line of the bill.
Four costs stack on top of the sale you already lost:
- The merchandise, which shipped and isn't coming back.
- The chargeback fee, charged per dispute whether you win or lose.
- Processing and network fees on the original transaction, which aren't refunded.
- The labor of pulling evidence and writing a response.
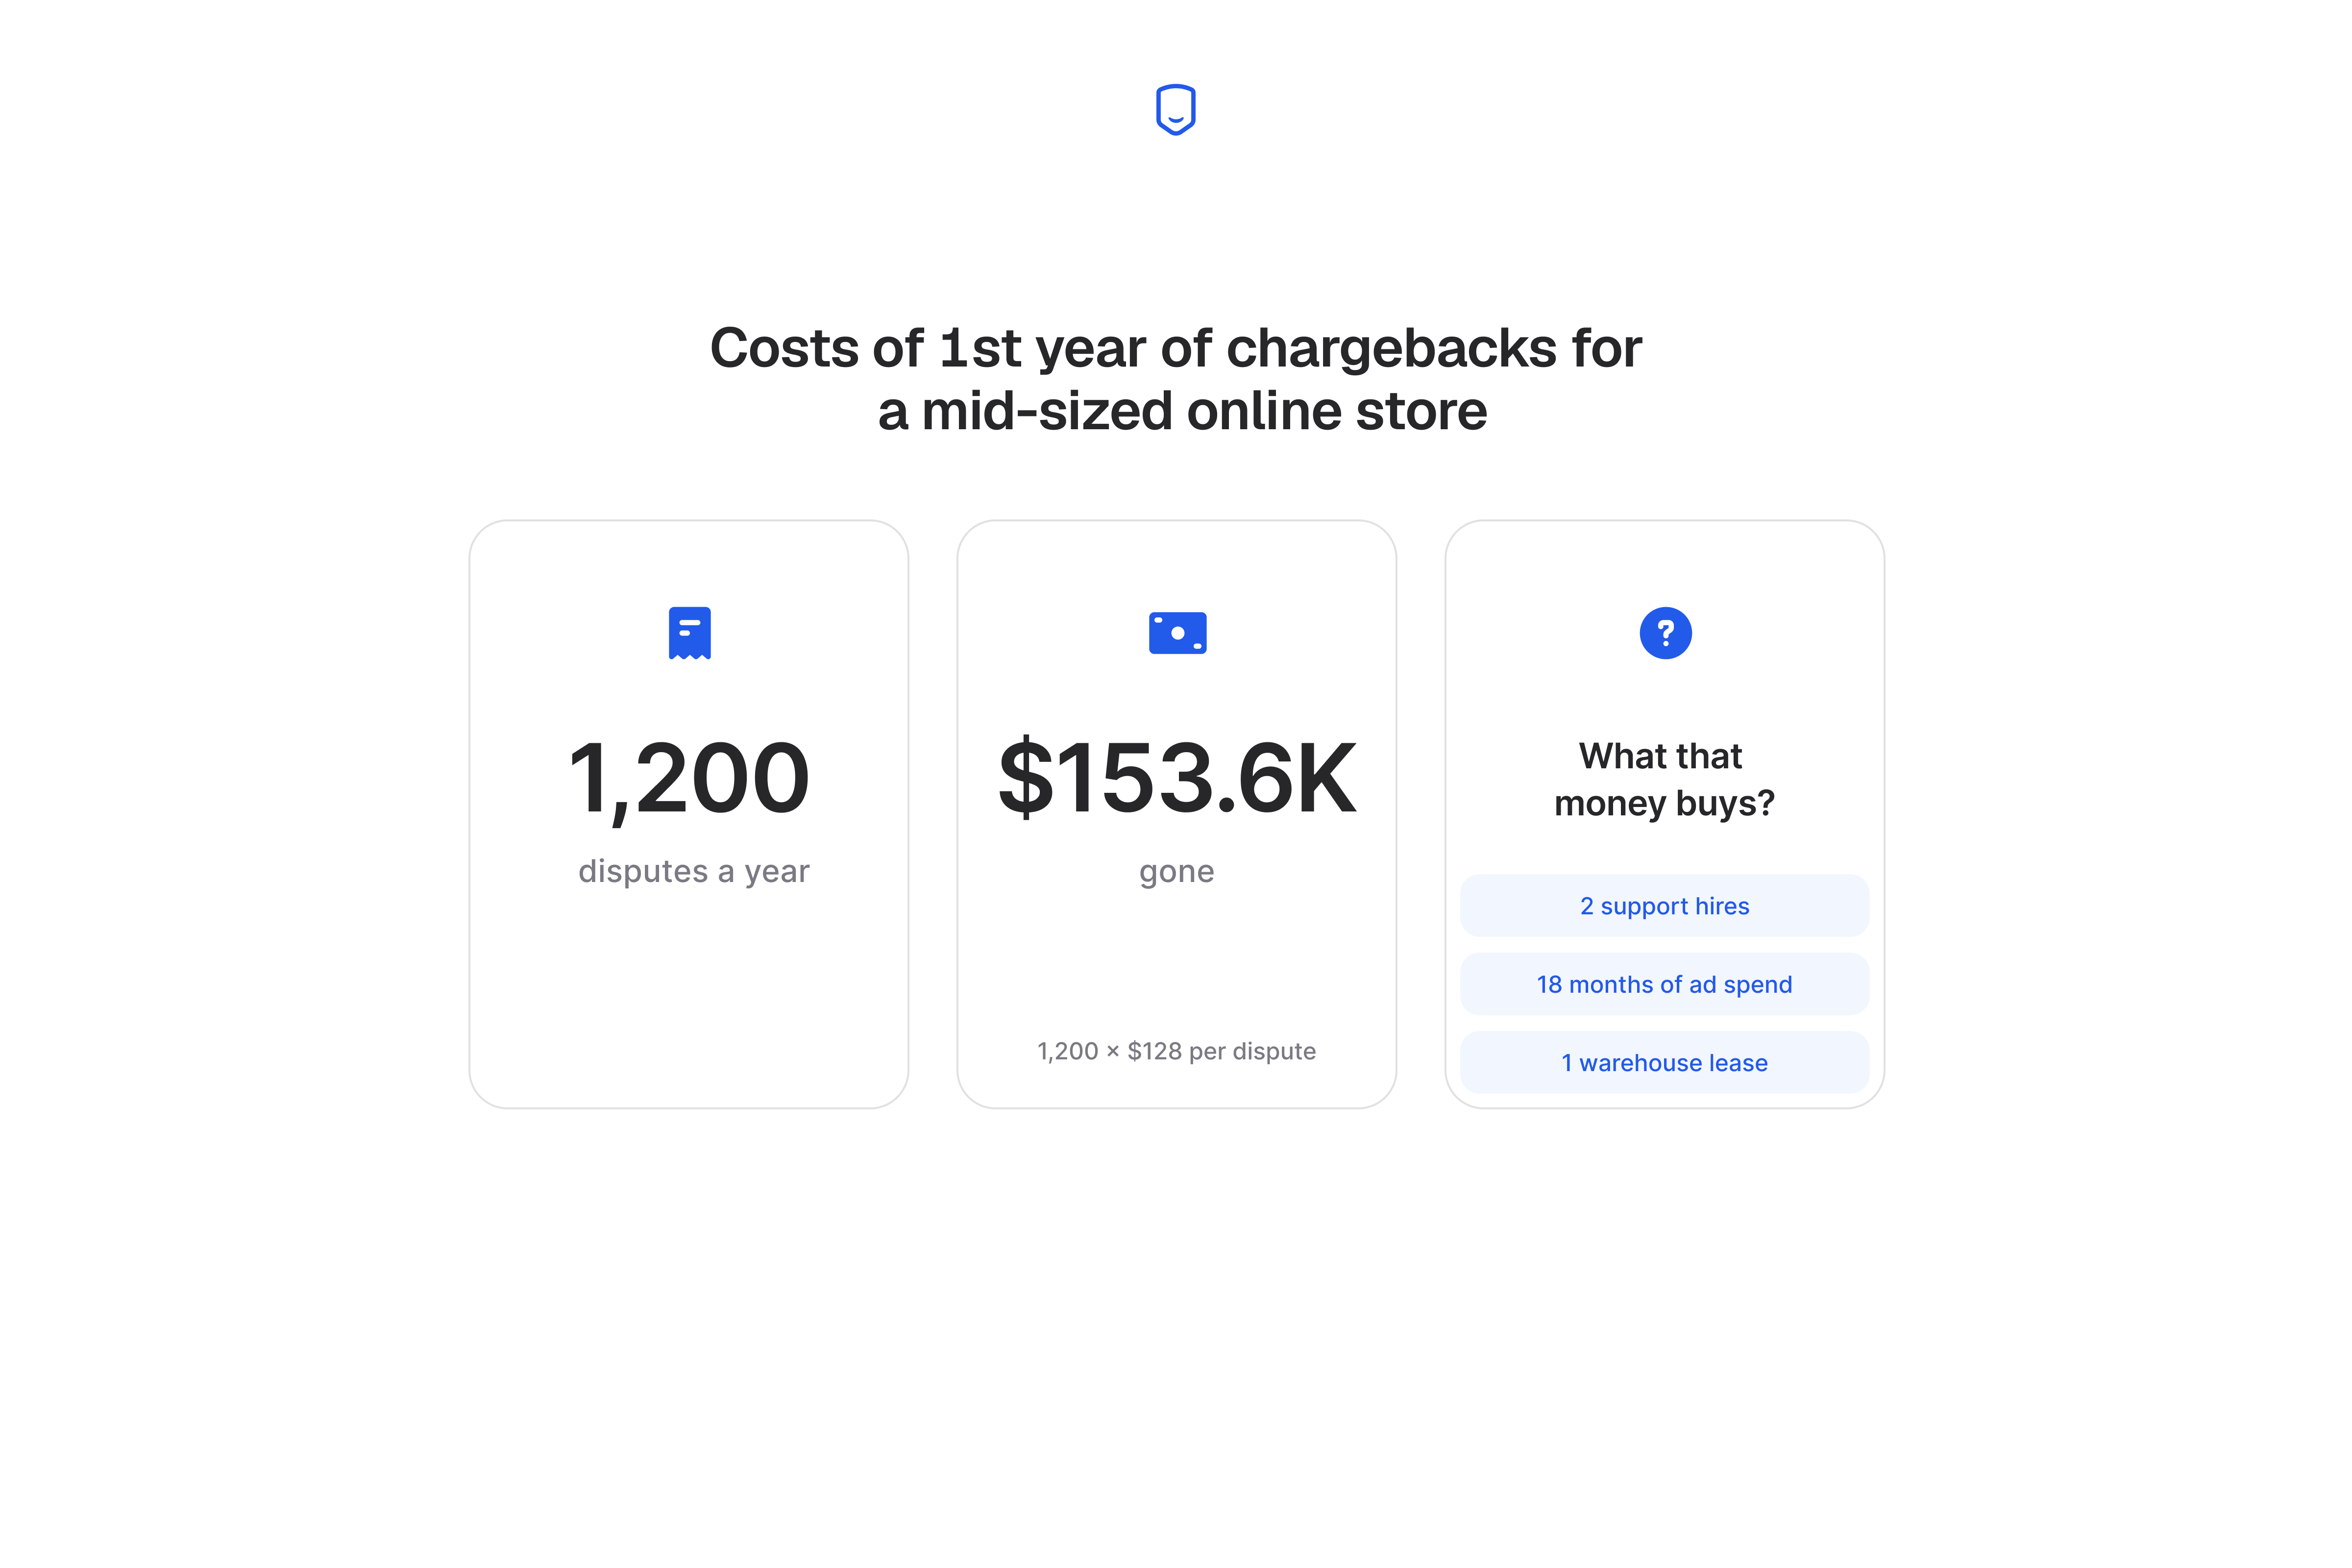
What merchants actually pay per chargeback
Merchants report $46 in third-party fees and $82 in internal costs per chargeback, about $128 all in. That cost scales with company size rather than shrinking:
Javelin's data shows the billion-dollar merchants pay the most per dispute at $233.01, because their processes involve more people and more systems. Internal labor is the bigger half of the bill at every size.
Average chargeback value by segment
According to Mastercard's segment data, a travel dispute averages $120. A subscription dispute averages $69. The amount varies by where and what you sell:
| Segment | Average chargeback value |
|---|---|
| Travel and hospitality | $120 |
| United States (all industries) | $110 |
| High-risk categories | $99 |
| Brazil | $94 |
| Retail | $84 |
| Digital goods | $77 |
| Subscription services | $69 |
Subscription disputes are the smallest at $69 and the most frequent, according to Mastercard's segment data. The same data puts the US average above $100.
Bank-side costs come back to you as well. According to Mastercard's research, issuers spend $9.08 to $10.32 on each dispute. They price that cost into the interchange and scheme fees you pay on every sale.
Whether you fight the dispute changes which costs you pay. Writing it off skips the labor line but gives up the sale outright. Fighting adds hours of work for a shot at getting the amount back, and neither path recovers the fee.
How often do merchants win chargeback disputes?
According to Mastercard and Datos Insights, US merchants win about 54% of the chargebacks they represent, counting only disputes they chose to fight. Representment means contesting a chargeback with evidence that the charge was valid.
That 54% figure, per Mastercard's data, counts a different set of disputes than the lower figures you'll see elsewhere. Issuers decide most disputes before a merchant responds. So a rate covering every dispute you receive looks worse than one covering the subset you fought.
Company size changes the odds too:
Larger teams tend to win more, mostly because they have someone whose job is building evidence packets.
Country matters too. Mastercard's data shows US merchants win 54% of representments, UK merchants 49.1%, and Australian merchants 46.7%, averaging 50% across the four countries surveyed.
The full US dispute funnel
According to Mastercard's US funnel data, merchants win 8.1% of all disputes outright, not 54%. The funnel shows where the rest go:
| Stage or outcome | Share of all disputes |
|---|---|
| Issuers win via chargebacks | 33.7% |
| Issuers win via representments | 29.9% |
| Issuers write off | 18.1% |
| Merchants win via representments | 8.1% |
| Resolved by memory joggers or merchant credit | 8.3% |
| Advance to arbitration or pre-arbitration | 1.9% |
Per Mastercard's funnel breakdown, merchants win just 8.1% of all disputes outright, even though they win 54% of the ones they fight. The gap is everything decided before a merchant ever responds.
Javelin puts the reason plainly:
"Issuers rarely have enough transaction context (shipping confirmation, item details, customer history) to adjudicate whether a dispute is legitimate before initiating a chargeback."
Javelin Strategy & Research, Chargebacks: The Case for Coordination (January 2026)
In other words, the bank is often deciding without the receipt, the tracking number, or the customer's order history.
From the cardholder's side the odds look completely different. Consumers who disputed a credit card transaction say they succeeded 89% of the time, and debit disputes succeeded 93% of the time.
Ignore a dispute and you lose it outright, so a merchant who fights nothing has no win rate at all. Response tactics by dispute type sit in our breakdown of how merchants win chargebacks.
Those odds are the argument for prevention. A dispute you never receive beats one you win a sixth of the time. That is why merchants use alerts to catch the charge and refund it before the issuer files anything.
What counts as a good chargeback rate?
A chargeback rate under 0.9% keeps most merchants clear of every card-network threshold, based on the Visa program minimums below. Each network sets its own line above that. Visa and Mastercard both count disputes as a share of transactions.
Go over the line and you get fees, reporting requirements, or an account review.
Mastercard's own minimums come from Chargebacks911's published thresholds page, since Mastercard's own PDF returns an access error to automated checks. Here is where each program draws it:
| Program | Network | Threshold |
|---|---|---|
| VAMP, Excessive (through 2026-03-31) | Visa | 2.2% combined fraud and dispute ratio |
| VAMP, Excessive (from 2026-04-01) | Visa | 1.5% combined fraud and dispute ratio |
| ECM | Mastercard | 100 to 299 monthly chargebacks, or 1.5% to 2.99% |
| HECM | Mastercard | 300+ monthly chargebacks, or 3% and above |
VAMP is Visa's Acquirer Monitoring Program, and it counts fraud and disputes together against your transaction count. ECM and HECM, defined by Chargebacks911's thresholds page linked above, are Mastercard's two tiers. A merchant can trip either one on the count or the rate, whichever comes first.
How VAMP counts your ratio
Two mechanics decide whether you enter a program at all. VAMP counts TC40 fraud plus TC15 disputes over settled transactions. It excludes disputes you resolved through pre-dispute tools like RDR.
There is also a floor. In the US, Canada, EU, and Asia Pacific, you need 1,500 fraud and dispute cases in a month before the ratio applies.
That exclusion is the part worth planning around. A dispute you head off with an alert never enters the numerator.
Our guide to the chargeback monitoring program covers what enrollment means.
Keeping your rate under 0.9% leaves room under all four, including Visa's lower April 2026 line.
None of these thresholds hold still. VAMP replaced Visa's older programs in 2025. Picture a merchant sitting at 1.8%, fine today and Excessive in eight months, without changing a thing.
If your rate is already above the benchmark, start with the descriptor on the customer's statement. Match it to the brand name they bought from and add a support phone number.
Then add dispute alerts, so the charges that still get questioned reach you before the issuer files them.
Summary: Stay under 0.9% for safety, and recheck against VAMP's lower 1.5% threshold before April 2026.
How to calculate your chargeback ratio
Your chargeback ratio is your chargebacks in a period divided by your transactions in that same period, as a percentage.
Say you process 50,000 transactions in a month and receive 150 chargebacks. That month's ratio is 0.30%.
Card networks are stricter about what goes in each half than most merchants are. The bottom counts settled transactions only. The top counts confirmed disputes only, so an angry email never enters it.
Timing catches people out too. Networks often measure the ratio over a trailing window. A dispute filed in June against an April sale lands in a different month than the sale. That alone can push a borderline merchant over a threshold.
Your acquirer or processor reports the official ratio it uses, so pull that number rather than trusting your own dashboard. Shopify's own changelog confirms it folds RDR-resolved disputes into the chargeback rate it shows by default as of January 2026, though merchants can still filter reports to see the rate without them.
Fees ride on top of the ratio. Stripe charges US merchants $15 when a dispute arrives and another $15 to counter it, returning the second fee only if you win.
For the counting rules in full, read our guide to how chargeback rate is defined.
Chargeback rates by industry
Average chargeback rates run from 0.12% in restaurants to just over 1% in education and training. Software and SaaS sit near the middle at 0.66%. Two comparisons follow below:
- By industry, where recurring billing and delivery risk set the spread.
- By country, where an older dataset still shows the regional gap.
1. Chargeback rate by industry
Education and training carries the highest average chargeback rate at 1.02%, and restaurants the lowest at 0.12%. Across all industries, the blended average sits at 0.26% as of Q3 2025, up from 0.21% a year earlier. Three things give an industry a higher rate:
- Recurring billing the customer forgets about between charges.
- Larger average tickets worth the time a dispute takes.
- Services a customer can claim were never delivered.
Restaurants sit at the bottom because the customer eats the meal in person and the ticket is small. Here is the full spread:
Treat your own industry's number, per Swipesum's rate table, as a baseline. A SaaS business at 0.66% is average for SaaS and still four times a restaurant's rate. Network thresholds apply the same way to both.
Our comparison of the average e-commerce chargeback rate breaks the retail end down further.
2. Chargeback rate by country
Brazil and Mexico carry the highest national chargeback rates at 3.48% and 2.81%, with the US at 0.47%. These figures come from a 2016 dataset, the most recent country-level comparison available, so treat the ranking as directional. Here is how the countries compare:
| Country | Chargeback rate (2016) |
|---|---|
| Brazil | 3.48% |
| Mexico | 2.81% |
| Russia | 0.82% |
| France | 0.65% |
| Germany | 0.54% |
| United Kingdom | 0.52% |
| United States | 0.47% |
| Canada | 0.42% |
| Netherlands | 0.40% |
| Spain | 0.24% |
| Japan | 0.18% |
The spread matters more than the absolute numbers here. In 2016, selling into Brazil and Mexico carried a very different dispute rate than selling into Japan. No newer country comparison has replaced it, and a gap that wide still moves your blended ratio.
Where the dispute comes from is a separate question from where you're based. In our dataset, 64.7% of alerts came from US cardholders. The UK follows at 13.5% and Canada at 7.4%.
How we sourced our data
The first-party figures here come from our own platform's data, anonymized and aggregated across roughly 1.8 million dispute alerts. These are alerts we received, so they describe our merchants rather than the industry.
We counted total alerts inside each category. Then we reported each as a share of the alerts with a recorded value there. If a field was blank, we left that alert out of that category's count. Every percentage below describes labeled alerts only.
The clearest example is the network split:
Mastercard's Ethoca is our single largest source, while the two Visa networks together carry the other 58%.
Alerts by card brand and processor
Visa and Mastercard account for almost 9 in 10 alerts we see. Here is the split:
| Card brand | Share of alerts |
|---|---|
| Visa | 50.5% |
| Mastercard | 37.6% |
| American Express | 6.9% |
| Discover | 5.0% |
Read that split with a coverage caveat. In our dataset, alert coverage is low for American Express, JCB in the US, and Discover, and absent for other brands. The real non-Visa and non-Mastercard share runs higher than 11.9%.
Processor concentration is sharper still. In our dataset, Stripe accounts for 80.9% of alerts with a recorded processor, and Shopify 16.6%. That shows where our merchants sell. Processor performance is a separate question.
No single issuing bank dominates. In our dataset, the top ten banks each hold 7.6% to 9.4% of alerts, with Bank of America highest. Canadian banks show up often, which follows the alert networks' coverage.
By merchant category, in our dataset, business services lead at 4.6% of alerts. Computer software stores follow at 2.9% and clothing stores at 2.0%. The category field splits across hundreds of codes, so no single one takes a large share.
How we counted each category
Each split has its own labeled base, and they differ a lot. Here are the counts:
| Category | Labeled base |
|---|---|
| Issuing bank | 1,813,474 alerts |
| Card brand | 1,813,469 alerts |
| Alert network | 1,812,015 alerts |
| Reason code | 1,134,085 alerts |
| Cardholder country | 818,164 alerts |
| Payment processor | 585,848 alerts |
| 3D Secure status | 250,707 alerts |
Because each base differs, don't multiply figures from two splits together. They cover overlapping but different sets of alerts.
One finding matters if you're weighing fraud tooling. Only 9.9% of the disputed transactions in our dataset had 3D Secure enabled. We have no overall 3DS adoption rate to compare it against. Treat it as a description of disputed transactions and nothing more.
What to do with these numbers
Compare three of your own numbers against the benchmarks above. Your chargeback ratio, your win rate, and your top reason code. Together they tell you whether you have a prevention problem, a response problem, or a billing problem.
A high ratio with mostly fraud-coded disputes points at prevention, since Datos Insights' data puts the win rate on those at only 17% of the time. A normal ratio next to a pile of cancelled-subscription codes points at billing and descriptors.
Start with the statement descriptor, since it costs nothing and closes the single largest source of avoidable disputes. Match it to the brand name the customer actually bought from and add a support phone number.
Then close the timing gap. Alerts reach you while the dispute still sits with the issuer. That gives you room to refund the customer before it counts against your ratio.
FAQ
What is the success rate of chargebacks?
According to Mastercard and Datos Insights, cardholders succeed in most disputes they file, since about 74% of disputes become full chargebacks. Merchants who contest one win it about 54% of the time in the US.
What percent of transactions actually end up as chargebacks?
According to Sift's benchmarking data, the blended average across industries is 0.26% as of Q3 2025. Individual industries range from 0.12% to just over 1%.
Can I get flagged if my rate looks low to me?
Yes, because networks count differently than most internal dashboards do. They use settled transactions and a trailing window, so your acquirer's official ratio can exceed the one you track.
Do won disputes still count against my ratio?
Yes, under several network programs a chargeback counts when it is filed, regardless of who wins. Winning recovers the money but does not remove the dispute from your count.
