Best Shopify Payments Alternatives in 2026


Stripe, Authorize.net, Square, and Adyen are the four processors most Shopify merchants switch to. Each one wins for a different reason. Some merchants need subscription billing, some need high-risk tolerance, some need omnichannel sales, and some need multi-method checkout.
I've investigated merchants' processor setups in a support role, across all four of these processors. That taught me how differently each one handles disputes. It also taught me where the disputes actually come from. They follow the transaction.
Pick by the limitation you're actually solving and the switch pays off. Choose on brand name instead, and you inherit a new fee schedule with the same chargebacks attached.
Key takeaways
- Switch to Stripe for subscriptions, Authorize.net for high-risk, Square for omnichannel.
- Choose Adyen when international customers need local payment methods at checkout.
- Budget 2.9% + 30¢ per transaction and $15 per dispute on Stripe.
- Expect $0 per dispute on Square and about $25 on Authorize.net.
- Add an alert layer separately, because no processor here prevents disputes.
Switching won't stop the disputes. Catch them first with Chargeback.io's alert coverage.
What is the best Shopify Payments alternative?
Stripe, Authorize.net, Square, and Adyen are the four leading Shopify Payments alternatives, and each fits a different switching reason. Stripe handles subscriptions and Authorize.net accepts high-risk categories. Square unifies in-person and online sales, and Adyen covers international payment methods.
So the right pick depends on which limitation of Shopify Payments you're solving.
A store that can't get approved at all needs a different answer than a store that can't bill monthly.
What none of them change is your chargeback rate, which the dispute-risk section below gets into.
Why merchants leave Shopify Payments
Merchants leave Shopify Payments when it can't process their category, bill monthly, take a local payment method, or sell in person. Every one of those is a capability gap, and price is rarely the trigger.
Shopify Payments is one processor with fixed eligibility rules. A business model outside those rules needs a processor built for its case.
Here's what actually pushes a store to switch:
- High-risk category: your business type isn't eligible to process at all.
- Subscription billing: you need recurring charges, retries, and metered usage.
- Your customers expect a payment method or currency Shopify Payments skips.
- Omnichannel selling puts in-person and online sales under one account.
Each reason maps to a different alternative below. Eligibility is a yes or no, and the other three are gaps you can measure.
If none of these describe your store, staying put is the cheaper call.
Switching means integration work, a third-party surcharge on every transaction, and a new dispute workflow to learn.
Our Shopify Payments integration page covers how alerts connect either way.
4 Shopify Payments alternatives compared
Stripe, Authorize.net, Square, and Adyen cover almost every reason a merchant leaves Shopify Payments. Each one is reviewed below against the switching reason it serves best.
Here's what each one costs to run:
| Processor | Base processing fee | Dispute fee |
|---|---|---|
| Stripe | 2.9% + 30¢ | $15 |
| Authorize.net | $25/mo + gateway rate | ~$25 |
| Square | 2.9% + 30¢ (online) | $0 |
| Adyen | Interchange++ (quoted) | Not published (bank-set) |
Take them in order, starting with subscriptions. Our full 8-gateway comparison has the wider view.
1. Stripe: best for subscription billing
- Who should get it:
- Stores billing subscriptions, renewals, or metered usage
- Merchants selling digital goods Shopify Payments protects poorly
- Teams with developers who want API control over checkout
- Processing fee: 2.9% + 30¢ per successful domestic transaction
- Dispute fee: $15 per case, win or lose
- Fraud tools: Stripe Radar, plus Chargeback Protection for an added rate
Pros
- Billing engine handles renewals and failed-payment retries
- Radar screening measurably cuts dispute rates
- Supports far more currencies than Shopify Payments
Cons
- You lose Shopify's chargeback-fee reimbursement
- Disputes move to Stripe's dashboard, not Shopify's
- Weak for in-person selling without custom work
Stripe is the best Shopify Payments alternative for subscription billing, because its billing engine and retry logic are built for renewals. Shopify Payments handles one-time orders cleanly and stops there.
Stripe charges 2.9% + 30¢ per successful domestic transaction.
Every dispute then costs $15 per case, win or lose.
Recurring billing also changes the shape of your dispute exposure. A renewal charges someone who isn't sitting at a checkout screen. The charge hits their statement weeks after they last thought about you. That's why cancelled-recurring disputes are so common.
Stripe Radar screens payments for fraud. Stripe reported a 17% reduction in dispute rates for Radar users last year.
Unless you run true subscriptions, you're paying for a billing stack you won't use.
2. Authorize.net: best for high-risk businesses
- Who should get it:
- Categories Shopify Payments and Stripe reject outright
- Merchants who can carry their own fraud and alert layer
- Stores prepared for a rolling reserve and tighter terms
- Processing fee: $25 a month on the all-in-one plan, with the bank setting your rate
- Dispute fee: Set by your acquiring bank
- Setup: Merchant-account approval first, then the gateway on top
Pros
- Connects to banks that accept high-risk categories
- Keeps you processing when other gateways decline you
- The bank relationship is yours, not the platform's
Cons
- No chargeback insurance, so you carry the dispute risk
- Expect a rolling reserve and more frequent rate reviews
- Approval takes days, and dispute fees aren't published
Authorize.net is the best fit for high-risk categories, because it connects to banks that accept business types Shopify Payments rejects. Getting approved at all is the whole reason to switch here.
The gateway runs $25 a month on its all-in-one plan. The acquiring bank behind it sets your processing rate.
Dispute fees can run around $25 per chargeback. Your bank's contract sets the exact figure, and Authorize.net doesn't publish one in its own documentation.
A high-risk merchant account also comes with tighter contract terms. Expect a rolling reserve, and an acquirer that reviews your dispute rate more often than it would a standard account.
Authorize.net leaves chargeback insurance to you, so budget for alert coverage from day one rather than after your first monitoring-program warning.
Setup is heavier too. You apply for the merchant account first, then connect the gateway on top, and approval takes days rather than an afternoon.
3. Square: best for omnichannel sellers
- Who should get it:
- Stores selling at a counter or market as well as online
- Merchants who want one payment record across channels
- Sellers who want no per-dispute fee
- Processing fee: 2.9% + 30¢ online on the Plus and Premium tiers
- Dispute fee: $0, with no separate charge per case
- Channels: In-person hardware and online checkout on one account
Pros
- No dispute fee, where most processors charge $15 to $25
- Counter and website run off a single account
- In-person hardware works out of the box
Cons
- A pure online store gains little from it
- A zero fee doesn't reduce how many disputes you get
- Thinner subscription billing than Stripe
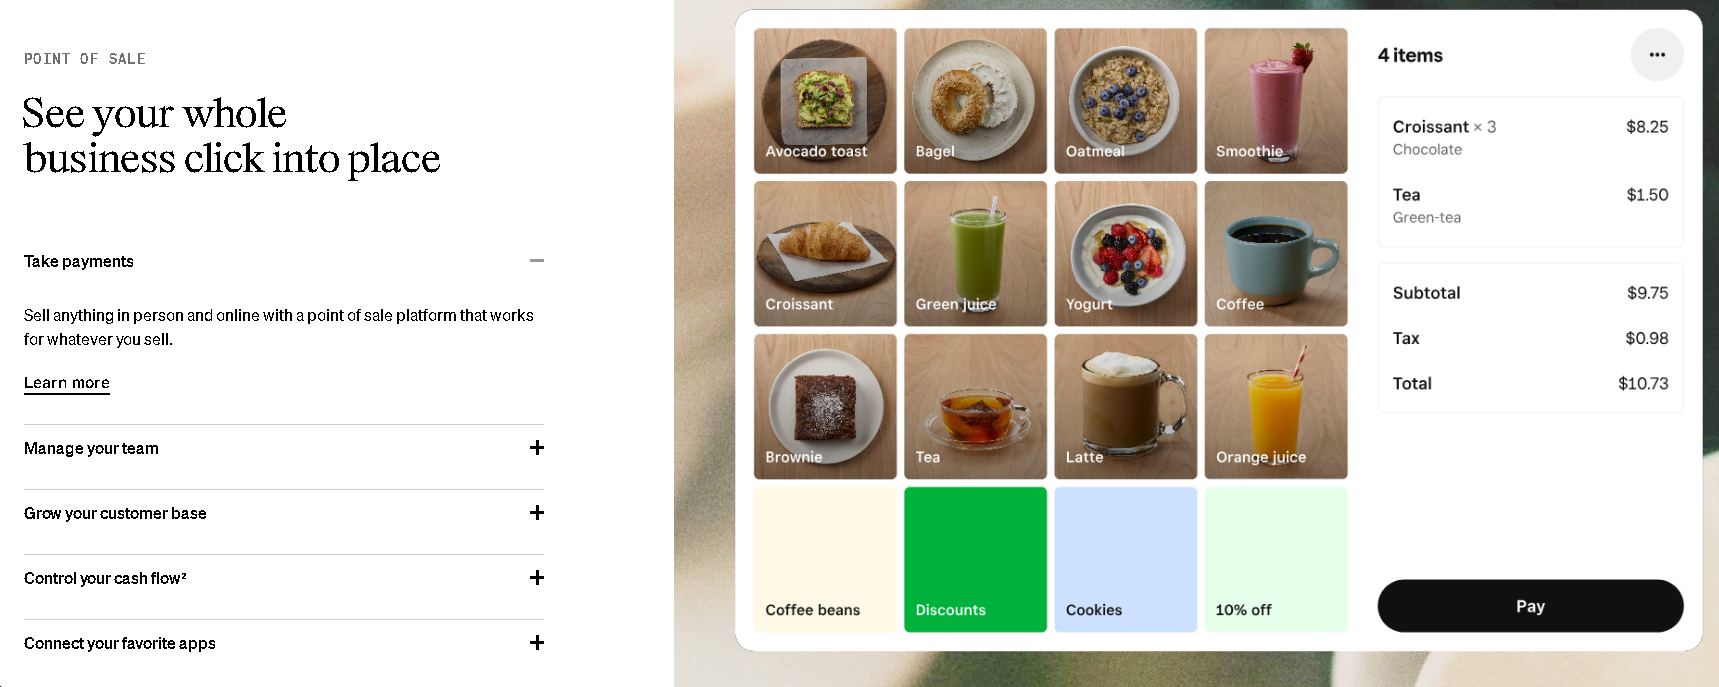
Square is the best fit for merchants selling in person and online, because it puts both channels under one account with one payment record. Sell at a market stall and on your site, and every sale lands in the same place.
Online card payments run 2.9% + 30¢ on Square's Plus and Premium tiers. Square handles disputes differently from the others, too.
Square's chargeback policy adds no separate dispute fee, where most processors charge $15 to $25 per case. You still lose the disputed sale, and Square spares you the fee on top.
That zero fee is easy to over-weight. It makes each dispute cheaper, and the number of disputes stays the same. A rising dispute rate still puts your account at risk with the card networks.
Square does one thing really well, which is running the counter and the website off one account. A pure online store gains little from it.
4. Adyen: best for multi-method international checkout
- Who should get it:
- International stores whose buyers expect local payment methods
- High-volume merchants who can negotiate Interchange++ pricing
- Sellers losing carts to a card-only checkout abroad
- Processing fee: Interchange++, quoted by card type, region, and volume
- Dispute fee: Not published, since it varies by region and acquiring bank
- Fraud tools: RevenueProtect transaction scoring
Pros
- Broadest local payment method and currency coverage here
- Interchange++ can beat flat rates at high volume
- RevenueProtect scores transactions for fraud
Cons
- Volume expectations rule out smaller stores
- Neither processing nor dispute pricing is published
- Quoted pricing makes cost hard to compare upfront
Adyen is the best fit for international stores, because it supports local payment methods and currencies that card-first processors skip. A shopper who can't pay the way they normally pay tends to leave the cart.
What shoppers expect keeps shifting toward wallets. In the US, digital wallets already run 40% of e-commerce transactions. The share runs higher in several European and Asian markets.
Adyen quotes Interchange++ pricing instead of a flat published rate, so your cost depends on card type, region, and volume. The dispute fee works the same way, and it varies by region and account with no single published figure.
Adyen's own knowledge hub quotes an industry-general $20 to $100 band charged by acquiring banks, and publishes no rate of its own.
Adyen also expects volume, which rules out smaller stores.
Its RevenueProtect tooling scores transactions for fraud, so it helps on the fraud-driven share of your disputes.
Chargeback and dispute risk by processor
Switching processors doesn't change your underlying dispute rate, because the transaction itself drives chargebacks. Four things decide whether a customer disputes:
- Product type, since digital goods and subscriptions draw more claims.
- Descriptor clarity, or whether the charge is recognizable on a statement.
- Fraud exposure, meaning how many stolen cards reach your checkout.
- Fulfillment, covering late, wrong, or undelivered orders.
A processor authorizes the charge. It doesn't touch any of those four.
Say your store runs a 1% dispute rate on Shopify Payments and you move to Stripe. You get the billing engine you switched for. Your dispute rate holds, because your customers and your fraud exposure are the same as they were last month.
A dispute is the cardholder questioning a charge with their bank. It becomes a chargeback once the bank forces the reversal. Our Shopify chargeback guide walks through that sequence.
Processor fraud tooling is the real exception.
Stripe Radar, Adyen RevenueProtect, and Square's risk tools all score payments before they charge. None of that touches a cancelled recurring charge or a claim that the goods never arrived.
One caveat on our own numbers. Most disputes we see come from Stripe and Shopify Payments merchants, which reflects who uses our platform. Read it as a map of where our alerts come from.
Only crypto payment processing sits outside the card networks entirely, and it costs you nearly every buyer who expects a card.
Do you still need chargeback prevention?
Yes. Every processor in this comparison still needs a separate prevention layer, because none of them resolve disputes before the bank turns them into chargebacks. Their fraud tools screen payments. Alerts catch the dispute already in motion.
The card network tells an alert network about a dispute, and the alert network tells you before your processor ever sees it. Ethoca alerts cover Mastercard.
On the Visa side, Verifi's RDR and CDRN do the same job. You refund the customer and close it out, whichever of the four processors you run.
Here's the setup that actually holds a dispute rate down:
- Fix the descriptor so it shows the storefront name buyers recognize.
- Turn on 3D Secure to shift fraud liability on verified payments.
- Add fraud scoring with a tool like Signifyd, Riskified, or Kount.
- Enable alerts through Ethoca and Verifi to refund inside the response window.
The first three cut fraud-driven disputes.
Only the fourth catches the customer who simply forgot.
Coverage has real gaps worth naming. Alerts reach few American Express, JCB, and Discover disputes, so expect them to catch most of your volume rather than all of it.
We built Chargeback.io's alert coverage to run across Ethoca and Verifi on one integration. The alerts arrive whichever processor you switched to.
Choosing the right alternative for your switching reason
Match the alternative to the specific limitation you're solving, and check eligibility before you compare fees. Each processor's rules and fee structure follow the use case it was built for. "Best overall" pushes merchants toward brand recognition instead of fit.
Work it in this order:
- Name the limitation that's actually pushing you off Shopify Payments.
- Check eligibility with the processors that solve it.
- Compare fees among whatever's left.
If you pick on price and the processor can't do the job, you'll migrate twice.
The framework assumes you have one main reason to switch. A high-risk store that also bills subscriptions usually accepts a tradeoff. Authorize.net's recurring billing is thinner than Stripe's, and Stripe rarely approves high-risk categories.
Ten minutes on the cost side before you commit is worth it. Our chargeback prevention ROI calculator puts numbers on what disputes are costing you today.
Five factors separate the shortlist once eligibility clears:
1. Availability in your country
Confirm the processor operates in your country before anything else, because Shopify Payments itself runs in only about two dozen. A merchant outside that list has no decision to make on Shopify Payments, and the same limit applies to some alternatives.
Check the currencies you settle in, not just the country you're registered in. A processor can support your market and still settle in a currency that costs you on conversion.
Summary: Check country and settlement currency before comparing anything else.
2. The real cost of switching
Add the third-party surcharge and the perks you give up to the new processor's rate, since the headline fee understates the switch. Shopify charges a surcharge on every transaction through an alternate provider. You also lose Shopify's chargeback-fee reimbursement.
Small rate differences matter more at volume. At low volume, the surcharge usually swamps whatever you save.
Summary: Count the surcharge and the lost fee reimbursement, not just the rate.
3. The capability you're actually buying
Buy the specific feature that Shopify Payments couldn't give you, whether that's recurring billing, high-risk approval, in-person hardware, or local methods. Each processor here was built around one of those, and the rest of its feature list is secondary.
An app can sometimes close the gap without a switch. Plugins carry their own cost and another account to manage, so weigh that against migrating.
Summary: Name the one capability you're buying, then check nothing else regresses.
4. Whether your business model fits
Check the processor's own eligibility rules against your model, because a category that gets declined ends the comparison. Gambling, CBD, supplements, and other high-risk categories struggle across mainstream processors, which is the whole reason Authorize.net exists in this list.
Customer expectations count as compatibility too. A checkout missing the method your buyers prefer loses the sale.
Summary: Eligibility is a yes or no, so settle it before you weigh anything.
5. Dispute handling and reliability
Compare how each processor handles disputes and how fast its support responds, since both cost you money during an incident. According to Chargeback.io and Chargeflow, the dispute fee ranges from $0 on Square to about $25 on Authorize.net. Where you manage the dispute changes too, moving off Shopify's dashboard onto the processor's.
Ask about rolling reserves before you sign. A processor that holds a share of your revenue changes your cash flow more than any fee.
Summary: Compare dispute fees, where you manage disputes, and reserve terms.
FAQ
Can I use more than one processor with Shopify Payments?
Yes, Shopify lets you keep Shopify Payments active and add a third-party provider or express checkout button alongside it. Shopify charges its third-party surcharge only on the transactions that run through the alternate provider.
Is there a payment gateway without a chargeback option?
No card processor can eliminate chargebacks, because the right to dispute belongs to the cardholder's bank rather than the processor. Only non-card methods like crypto payment processing sit outside the card networks entirely.
Does Shopify Payments charge a chargeback fee?
Yes, Shopify Payments charges a per-dispute fee on US accounts and refunds it if you win. The amount is set per country, so it differs outside the US.
What if Shopify Payments suspends me for chargebacks?
Shopify can hold payouts or suspend processing once your dispute rate crosses the card networks' monitoring thresholds. Switching to a high-risk processor gets you charging again, though the dispute rate follows you until you fix it.