
How to Win a Chargeback as a Business


A business wins a chargeback by answering the bank's reason code with matching proof, filed on time. I've built representment evidence for disputes on my own stores, and about a third of contested disputes go the merchant's way.
The first chargeback I fought, I sent everything I had and still lost. I had skipped the reason code, so none of it answered the question the bank asked. That loss taught me the real leverage. It's knowing which disputes are worth fighting at all.
Key takeaways
Tired of fighting the same dispute twice? Our chargeback alerts let you refund the customer before a chargeback ever lands.
How do you win a chargeback as a business?
You win a chargeback by matching your evidence to the bank's reason code and filing before the response deadline. A thin packet with the right papers beats a thick one aimed at the wrong question.
Roughly a third of contested disputes end in the merchant's favor, and the odds shift with the industry, the evidence on hand, and the size of the charge. Not every chargeback is worth fighting, since some cost more in staff time than they recover.
The bank judges your response against one code's rules. Proof of delivery answers a code about goods that never arrived, while a code about an unapproved charge needs AVS results and device records instead.
Winning returns the disputed amount and nothing else. You keep paying the fee and the staff hours, and the dispute still counts against your ratio.
That's why the decision of whether to fight comes before the question of how.
Some chargebacks can't be won at any level of effort. A refund you agreed to and never sent leaves you nothing truthful to file.
Our breakdown of why a response gets denied covers the rest of those dead ends.
Should you even fight this chargeback?
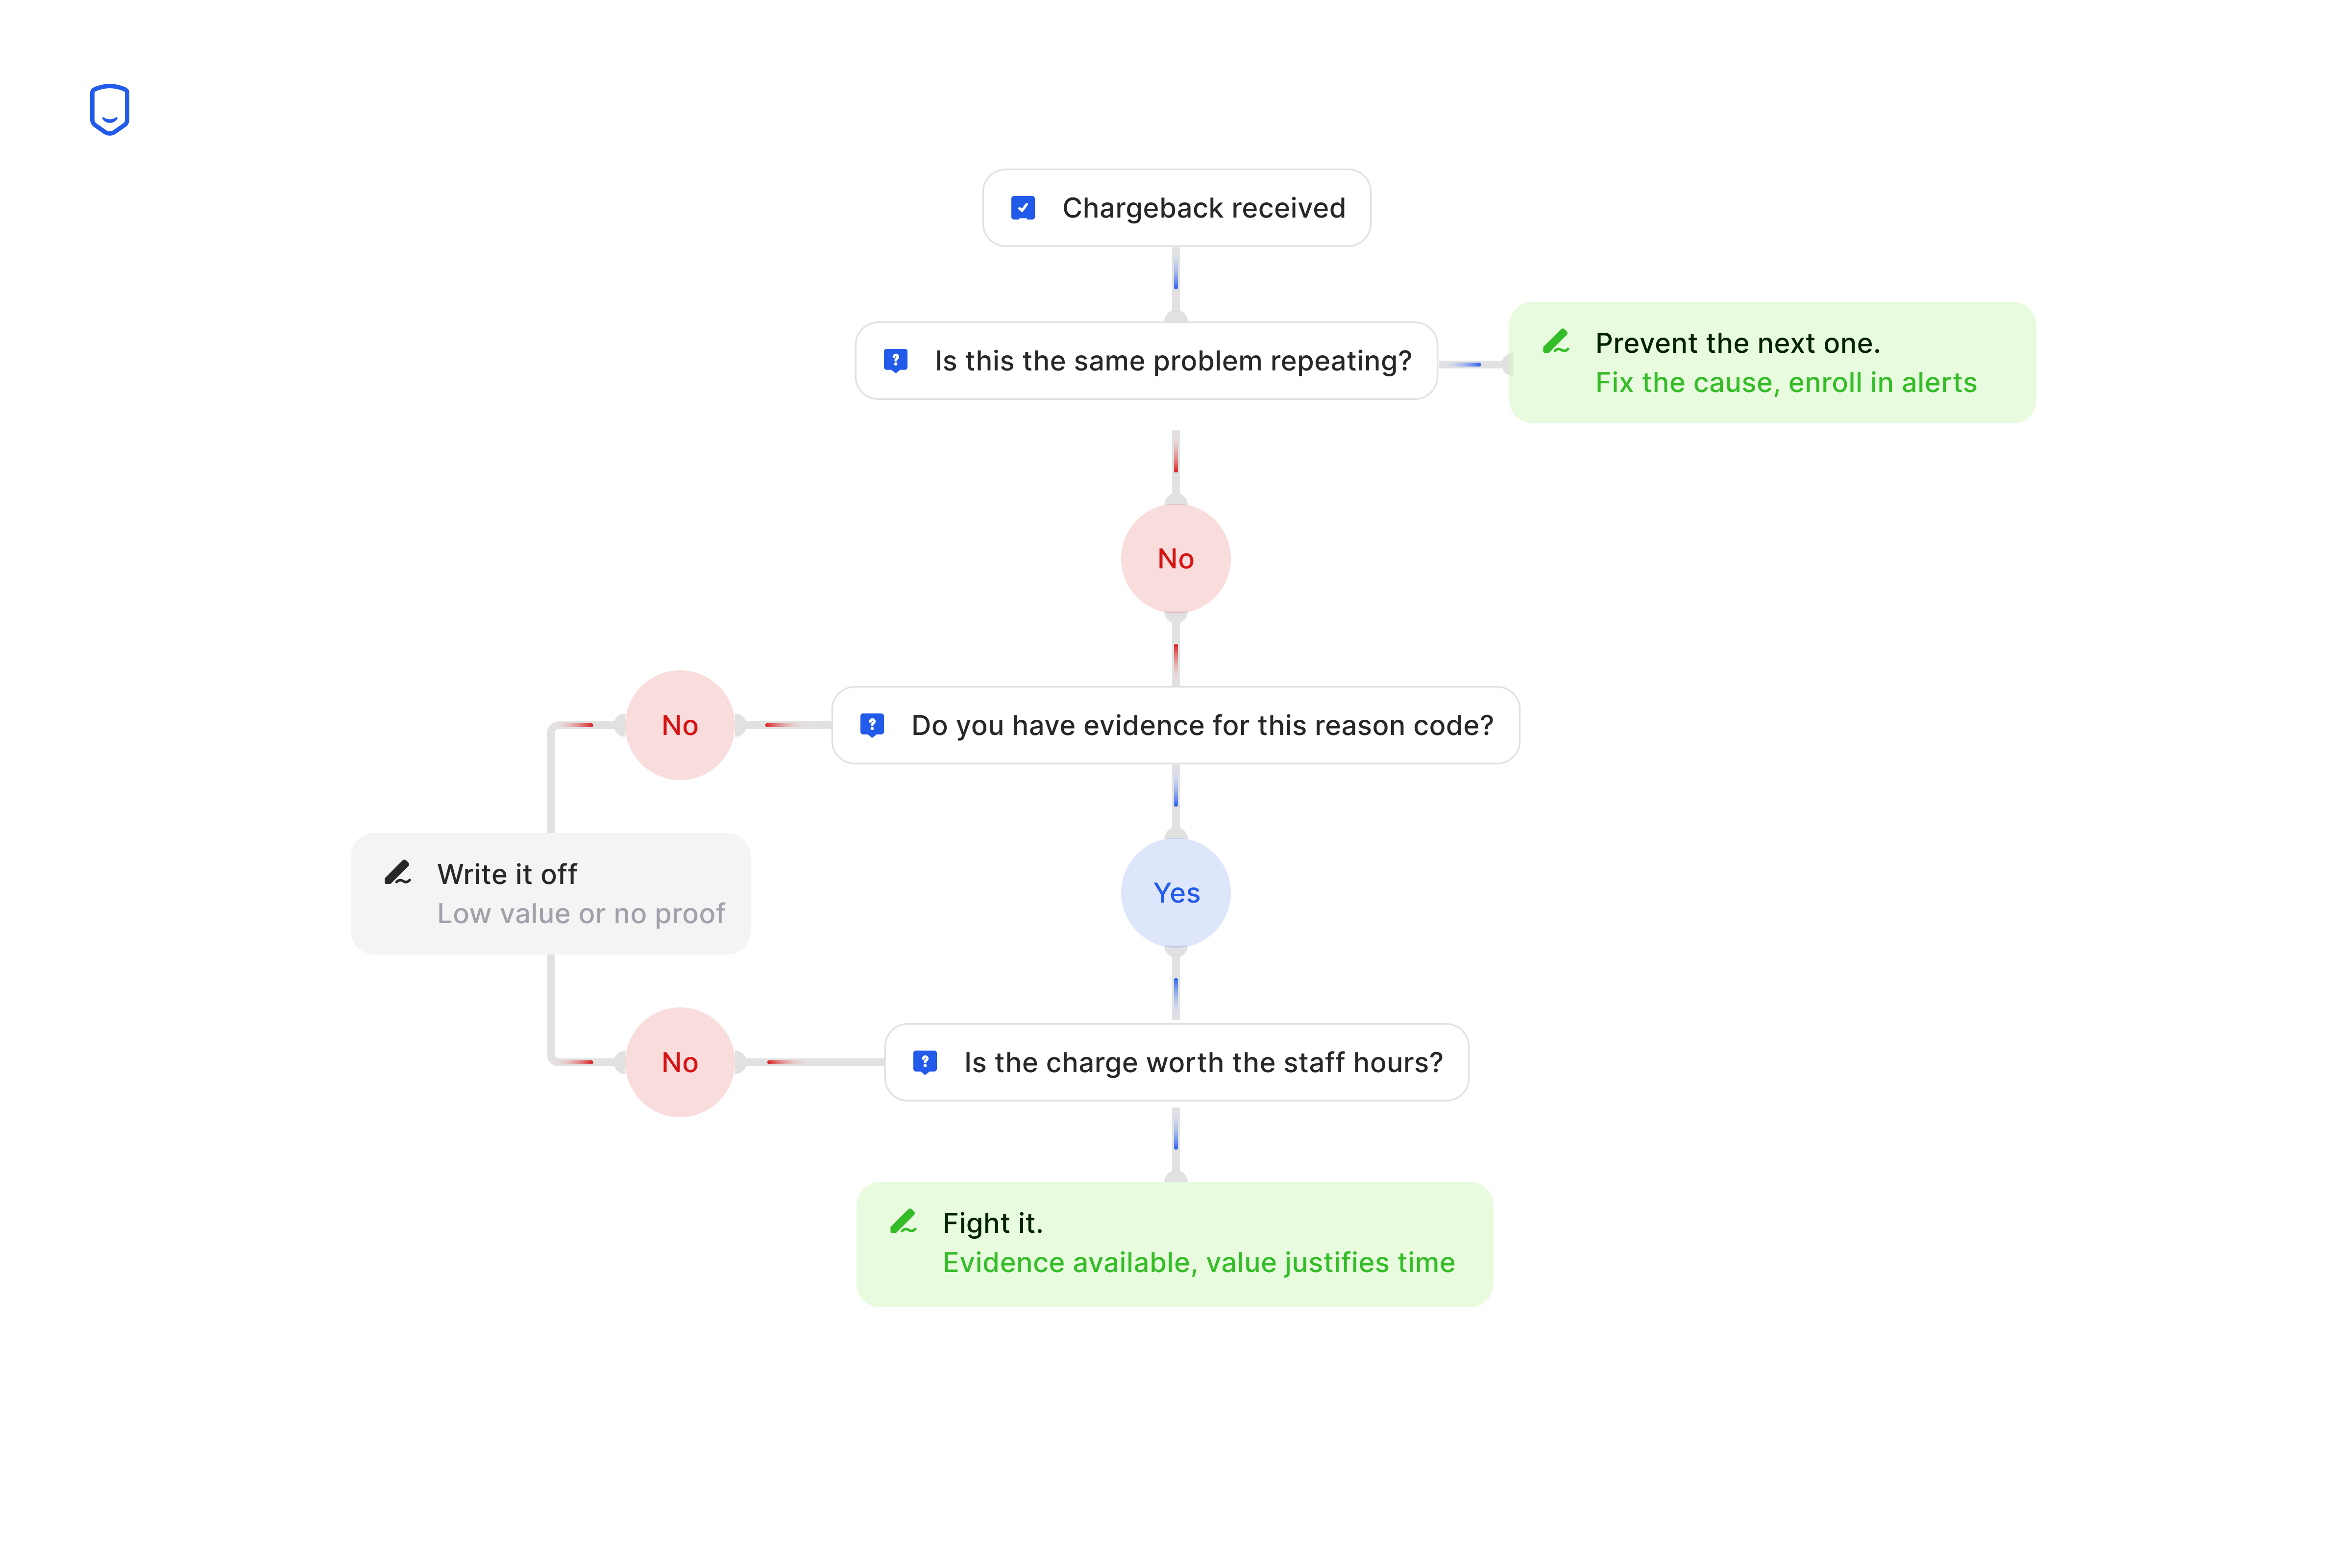
Fight the chargeback when you hold evidence for the cited code and the charge is worth the staff hours. Otherwise write it off, or fix what keeps producing the dispute. Three options:
- Fight it when the evidence exists and the money justifies the hours.
- Write it off when the charge is small or the proof isn't there.
- Prevent the next one when the same problem keeps producing disputes.
This assumes the bank already assigned a code. A dispute still in the pre-chargeback window is a different call.
1. Fight it
Fight the chargeback when your evidence answers the cited code and the charge is worth the hours. Both conditions have to hold.
Say a $30 charge eats the same staff time as a $900 one. The hours are identical, only the payoff changes.
Work out your own cutoff once and reuse it. Three steps get you there:
- Time one full response, from opening the notice to submitting the packet.
- Multiply those hours by what an hour of that person's time costs.
- Write off anything below the figure you land on.
With the cutoff set, the call on any new dispute takes about ten minutes. Read the code, check whether the matching record exists, and compare the charge to your line.
One exception is worth writing down. A code you're seeing for the first time can be worth answering below the cutoff, because the response shows you which records your system actually captures.
Write the cutoff into your dispute-handling process and name the person who applies it without escalating. A rule anyone has to escalate stops being a rule, and the deadline runs while the question waits for an answer.
2. Write it off
Write off the dispute when the charge sits below your cutoff or your records can't answer the code. You stop spending on a case you'd lose.
The chargeback still counts toward the ratio your processor watches. If you write off everything, that ratio climbs and your processor notices.
Accepting a dispute closes it immediately.
The provisional credit the bank gave the customer becomes permanent, your processor keeps its fee, and no further deadline applies to you.
Log every write-off in a spreadsheet with the date, amount, and reason code. That turns a pile of small losses into the pattern that tells you what to fix, and the codes that repeat are the ones worth engineering out.
3. Prevent the next one
Fix the cause when several disputes in a month cite the same complaint. Answering them one at a time leaves whatever produced them running.
Sort last month's disputes by reason code and take the code with the highest count first. Each common complaint points at a fix you control:
| Complaint | What it usually means | The fix |
|---|---|---|
| Unknown charge | Your billing descriptor doesn't match your storefront name | Change the descriptor in your processor's dashboard |
| Never received | You have no delivery confirmation on file | Turn on signature-required delivery above your average dispute value |
| Unexpected renewal | The customer got no warning before the charge | Enable the renewal-reminder email in your billing tool |
Tim's Coffee turned the same logic into a standing rule. The Shopify retailer auto-refunds disputes under $300 and fights anything over it, so dispute handling runs as a policy rather than a fresh judgment call each time.
Their Tim's Coffee case study shows how that rule works alongside alerts.
Prevention also changes what the other two options cost you. Fewer disputes reach the chargeback stage, so your hours go to the cases worth fighting.
The cheapest win is the dispute that never becomes a chargeback, which is what preventing chargebacks before they happen is built around.
How to win a chargeback as a business: the process
Read the reason code first, then gather only the records that answer it and file before your processor's cutoff. Five steps take you from the notice to a submitted response:
- Check the reason code and confirm what it asks you to prove.
- Resolve disputes before they become chargebacks while the window is still open.
- Gather evidence your business type can actually produce.
- Check deadlines on every clock running against the case.
- Write the rebuttal letter that ties the packet together.
Run them in order. Each step tells you what the next one needs.
1. Check the reason code
The reason code is the question the bank wants answered, and it sits on your dispute notice. Read it before you touch a single document. Each network runs its own numbering. Our guide to chargeback reason codes maps what each family asks for.
Each code belongs to a family, and each family asks its own question:
- Fraud codes ask who approved the payment.
- Product codes ask whether the customer got what they bought.
- Processing codes ask whether the charge was correct.
Answer the wrong family and the bank never reaches the merits.
The bank recodes what the customer tells them. A shopper who forgot a subscription describes it as an unknown charge, and the issuer files that as fraud. Your job becomes proving authorization, so read the code as the question you must answer.
Write the code number down before you start pulling files. Our reason code lookup tool decodes it by network in seconds.
2. Resolve disputes before they become chargebacks
Refund the dispute early and it closes as a plain refund. The customer calls their bank first, and depending on the network you may get a window to settle before money moves. Three things widen that window:
- Answer refund requests inside one business day.
- Put your storefront name and a contact number in the billing descriptor.
- Enroll in dispute alerts so you hear about complaints early.
Most disputes start with a customer who tried to reach you and gave up. A same-day reply usually turns a would-be chargeback into an ordinary refund.
The descriptor is where most of these start.
A customer scanning a statement sees the string your processor sends, and a legal entity name they have never heard of reads as fraud to them. Set it in your processor's dashboard, then buy something from your own store and check how it lands on the statement.
A dispute alert buys you the same window without the guesswork. The alert tells you a customer has complained to their bank, and refunding inside the response window stops the chargeback from being filed. That costs you the sale while keeping the fee and the ratio damage off your account.
3. Gather evidence (by business type)
Pull the records your business type generates, then keep only what speaks to the cited code. What counts as strong proof depends on what you sell:
| Business type | Evidence that carries weight |
|---|---|
| E-commerce and physical goods | Signed delivery confirmation, tracking with timestamps, product photos and listing copy, the return policy shown at checkout |
| Hospitality, travel, and events | Booking confirmations, check-in or no-show records, cancellation terms the guest accepted, ID captured at arrival |
| Subscriptions and digital products | Login and activity logs, IP and device records, the terms accepted at signup, renewal notices you sent |
| In-person retail | Signed receipts, register and terminal records, security footage, the pickup form the customer signed |
Two records are worth capturing before you ever need them.
Store the AVS and CVV results with every sale, because gateways purge them on their own retention schedule and a fraud code can arrive months later. Get signed delivery proof on anything priced above your average chargeback.
Put the two records that answer the code on page one. A reviewer working a queue reads the first page properly and skims the rest, so the exhibit order decides what actually gets read.
Screenshots need context to count as evidence. A chat message proving the customer received the order should show the timestamp, the customer's identifier, and enough surrounding thread to show the message is complete.
4. Check deadlines
File by your processor's cutoff, which lands days before the card network's outer window. Three separate clocks run against the same case:
| Clock | Who sets it | When it starts |
|---|---|---|
| Network response window | The card network | The day the chargeback is filed |
| Processor cutoff | Your acquirer, ahead of the network's | The day your processor posts the dispute |
| Third-party record lead time | Carriers and gateways you request files from | The day you ask |
Set a calendar reminder at the halfway mark of the shortest window. A 20-day window should prompt you on day 10, while you can still chase a missing file.
Count from the date your processor posts the dispute. A notice sitting unread in a shared inbox burns the same days as one you're working on, so route dispute notifications to one named person.
Request third-party records the day the notice lands. Carrier delivery confirmations and gateway archive pulls arrive on their own schedule, and that wait is what usually costs merchants the window.
5. Write the rebuttal letter
The rebuttal letter tells the reviewer which attached file answers which part of the claim. Reviewers work through a queue on a clock, so the letter has to point them straight to the right file. Four parts, in order:
- State the reason code and the claim it makes.
- Take the claims in the order the reason code lists them.
- Name the file answering each claim, with its page number.
- Close with the outcome you want.
Keep the letter to one page and back every argument with a named file.
Write it for a stranger. The reviewer has never seen your store or your policies, so spell out order numbers and product names in full.
Argue from your records. A letter showing login timestamps after the disputed charge reads as proof, while one arguing the cardholder is lying reads as a complaint.
After your first win on a code, save that letter with the case details replaced by placeholders. The next dispute only needs the code, the claim, and the exhibit list swapped in.
What are the odds of winning a chargeback dispute?
Roughly a third of contested chargebacks end in the merchant's favor, and apparel sellers beat that at a 35.81% win rate. Odds shift with how provable the claim is.
That spread has a cause. Answer an "item not as described" claim with product photos and the original listing, and a seller already holds both.
A fraud code asks you to prove the cardholder approved the charge. That means AVS results and device records many small sellers never captured. Sellers who logged that data at checkout win these disputes, and the rest lose them.
Averages hide a lot here. A big dispute coded for fraud carries far worse odds than a small product complaint, so a blanket "always fight" policy costs money. The fight, write-off, prevent test above beats any single win-rate number.
Your own rate is the number that matters.
Log every dispute you fight and how it ended, then group the losses by reason code after ten cases. Check which record was missing from each packet, because a code that repeats points at a gap in what your system captures.
Whoever published a win rate probably counted differently than you do. Some figures count only disputes the merchant chose to fight, which excludes everything written off and flatters the number.
Summary: About a third of contested chargebacks are won, with the odds set by whether your records answer the code.
Should you hire someone to win chargebacks for you?
Hiring a chargeback management company pays off once the vendor's cut costs less than your own staff hours. Below that line, handling disputes yourself or writing them off is cheaper.
Vendors charge a share of what they recover, or a flat fee per dispute, so their cost climbs with every case. Your own cost per response falls as your team gets faster and reuses its letter template.
That gap makes the crossover point calculable, and these signs tell you which side of it you sit on:
| A vendor earns its fee when | Handle it yourself when |
|---|---|
| Responses crowd out other work | An hour a week clears your queue |
| Your disputes span several processors | Most disputes fall below your cutoff |
| Nobody on staff has read a reason code | One fixable cause drives the repeats |
Multiply your monthly dispute count by your cost per response, then compare that to the vendor's quoted percentage of your disputed volume.
Our overview of chargeback management companies covers what the category handles.
Read the contract before the pricing. Four questions decide whether the quote is real:
- What counts as a recovered dispute?
- Does the fee apply to cases the bank would have reversed anyway?
- How long does the agreement run?
- Who writes the evidence, you or them?
That last one matters most. Some vendors file whatever you upload, so you still do the work that decides the case.
What happens after you respond to a chargeback?
After you submit, the bank either reverses the chargeback, upholds it for the cardholder, or the issuer files a second chargeback. The decision usually takes several weeks. Each outcome leaves you somewhere different:
| Outcome | What happens to the money | What's left |
|---|---|---|
| Reversed | The disputed funds return to your account | The fee, and the dispute on your ratio |
| Upheld | The customer keeps the credit permanently | The fee, the goods, and the dispute on your ratio |
| Second chargeback | The funds stay reversed while the case reopens | A choice about arbitration |
Networks count disputes filed, so the case stays on the record behind chargeback monitoring programs whichever way it lands.
Intake screens your response before a reviewer sees it. A late filing, or proof aimed at the wrong code, is discarded there, which is why the deadline and the reason code decide the case.
A second chargeback is the outcome merchants plan for least.
The issuer can come back once more if it reads your evidence as missing the point. Answering that round means arbitration, where the losing side pays the network's case fee on top of the disputed amount. Decide in advance what amount justifies going that far.
A reversal posts as a separate credit in your processor's payouts, often weeks after the ruling. Reconcile against the payout record.
Summary: A win returns the money but not the fee, and the dispute counts toward your ratio either way.
FAQ
How many chargebacks before a business gets flagged?
According to Visa and Mastercard's current monitoring-program rules, both networks start flagging merchants around 1.5% of monthly transactions. The exact cutoff varies by program and region, and crossing it puts you into a monitoring program with fines and required fixes.
What happens if you lose a chargeback dispute?
The disputed funds stay with the cardholder permanently and the chargeback fee remains on your account. The bank's decision is usually final, since arbitration adds the network's case fee on top of what you already lost.
What are valid reasons for a chargeback?
Valid grounds include unapproved charges, goods never delivered, items that differ from the listing, and billing errors like duplicate charges. Anything outside those groups is usually a customer skipping your refund process.
Can you fight a chargeback without any evidence?
A rebuttal needs at least one document that answers the cited code. With nothing to attach, writing the dispute off and fixing what caused it is the better use of the time.
Does losing a fought chargeback hurt your merchant account?
Losing a dispute you fought carries no penalty beyond the staff hours you spent on it. The chargeback already counted against you the day the customer filed.
